Grandparent-Owned 529 Savings Plans: The Benefits of Recent Changes
Helping a grandchild pay for college can be a pretty rewarding way to use your money.
You get to help someone you love, potentially reduce the amount they’ll need to borrow, and make a meaningful gift while you’re still around to see the impact.
And recent changes have made one of the best-known college savings tools, the 529 plan, even more interesting for grandparents.
Grandparents have always been able to own 529 accounts. But changes to federal financial aid rules have removed one of the biggest drawbacks of doing so. At the same time, other changes have given families more options if a grandchild doesn’t ultimately need all the money for college.
If helping with a grandchild’s education is part of your financial or estate plan, grandparent-owned 529s are worth another look.
College Isn’t Getting Any Cheaper
No surprise here.
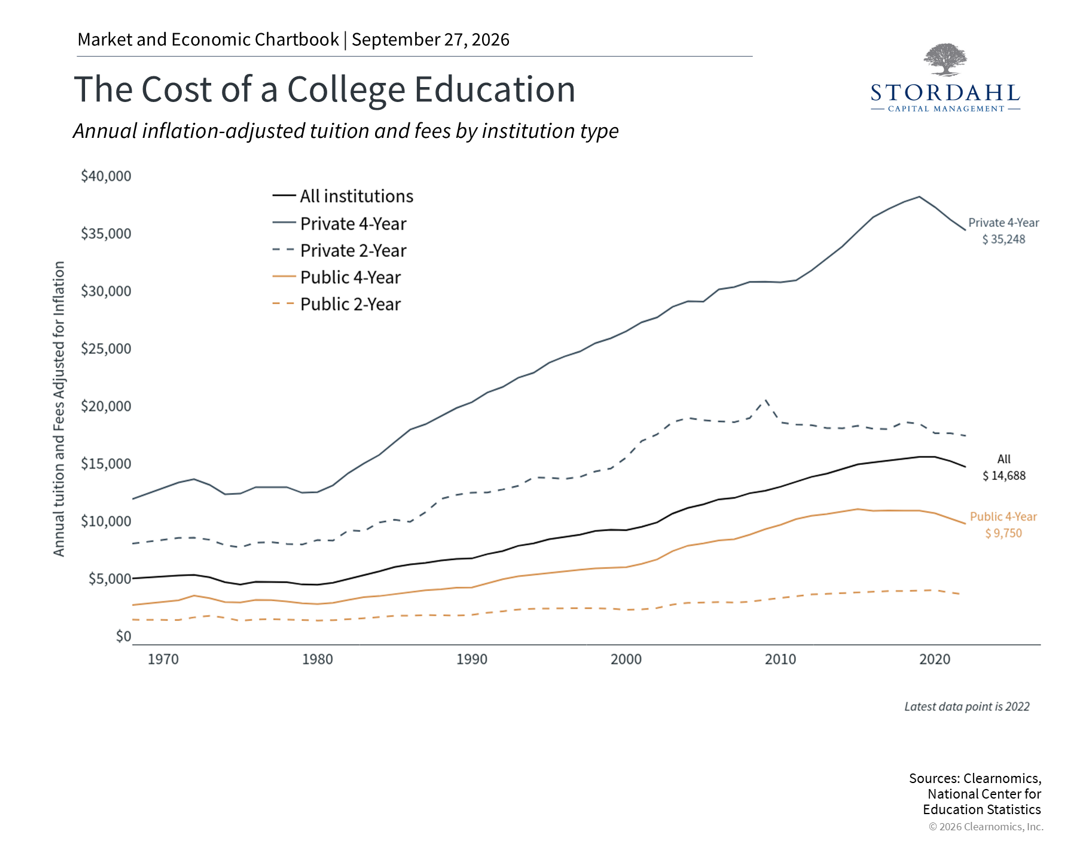
College is expensive, and tuition is only part of the bill. Families also have to account for housing, food, books, transportation, and other expenses. Those additional costs now average more than $17,000 per year.
The rising cost of a college education
Most families will pay for college from several sources: savings, current income, scholarships, grants, loans, and sometimes help from grandparents.
The question is how best to provide that help.
The Big Change for Grandparent-Owned 529s
Historically, there was a potential downside to a grandparent owning the 529.
Under the old FAFSA rules, distributions from a grandparent-owned 529 could be treated as student income. That could reduce the amount of need-based financial aid the student qualified for in a subsequent year.
In other words, Grandma and Grandpa could be trying to help with college and inadvertently make the financial-aid picture worse.
That has changed.
Under the current FAFSA methodology, distributions from a grandparent-owned 529 are no longer treated as student income in the same way. That removes one of the major historical disadvantages of having the grandparent own the account.
For some families, that’s a pretty big deal.
Why Own the 529 Yourself?
You don’t have to.
A grandparent can contribute to a 529 established by the child’s parents. But there can be advantages to establishing and owning the account yourself.
The biggest is control.
As the account owner, you retain control over the assets, including when distributions are made. You also have flexibility to change the beneficiary to another qualifying family member if plans change.
And plans have a habit of changing over 10, 15, or 20 years.
A grandchild might receive a scholarship. They might attend a less expensive school than expected. They may choose a different educational path altogether.
That doesn’t necessarily mean the money you saved goes to waste.
What If You Save Too Much?
This has always been one of the biggest concerns about funding a 529.
What happens if there’s money left over?
There are more options today than many people realize.
Under SECURE 2.0, up to $35,000 from a 529 may potentially be transferred to the beneficiary’s Roth IRA over their lifetime without federal income tax or the usual 529 withdrawal penalty, provided certain requirements are met.
Among them, the account must have been open under the beneficiary’s name for at least 15 years, and annual Roth IRA contribution limits and earned-income requirements still apply.
Think about what that could accomplish.
You start saving to help a grandchild with college. They don’t need all the money. Some of what remains may eventually help give them a head start on retirement.
That’s a pretty nice Plan B.
529 assets can also be used to repay up to $10,000 in qualified student loans, subject to the applicable rules.
And beginning in 2026, up to $20,000 per year per grandchild can be withdrawn tax-free for qualifying K–12 tuition.
The larger point is that 529s aren’t quite as restrictive as many people still assume.
529s Can Be an Estate-Planning Tool, Too
For grandparents who have accumulated more than they expect to spend, a 529 can serve another purpose.
It can be a way to start transferring wealth to the next generation during your lifetime.
For 2026, a grandparent can generally give up to $19,000 per grandchild without triggering federal gift-tax reporting. 529 plans also have a special provision that allows you to front-load five years of gifts into a single contribution, up to $95,000 for an individual, subject to the applicable rules.
That can accomplish several things at once.
You’re helping fund something meaningful. You’re giving the money more time to potentially grow tax-free. And you’re beginning to transfer some of your wealth in a purposeful way.
Depending on where you live, there may also be a state income-tax deduction or credit available for 529 contributions. Those rules vary by state and, in many cases, depend on which state’s plan you use.
Don’t Let Generosity Get Ahead of the Plan
Helping your grandchildren is wonderful.
Running out of money because you were too generous isn’t.
Before making a large 529 contribution, we want to understand what that money means to your financial plan.
Do you have enough to support the retirement you want? What happens if you live into your 90s? What about healthcare or long-term-care expenses? Are there other children or grandchildren you want to help? How does the gift fit into your estate plan?
Just because you can make a large contribution doesn’t mean you should.
For one family, $95,000 may be entirely reasonable.
For another, it could put unnecessary pressure on their own retirement.
The 529 is the tool. Your financial plan tells us how—or whether—to use it.
A Gift You Get to See Put to Work
There’s something we like about helping grandchildren with education.
It’s a form of legacy planning that doesn’t require you to wait until you’re gone.
You may get to see your grandchild head off to school. You may see them graduate with less debt. You may even get to see what they do with the opportunity you helped provide.
That’s different from simply leaving more money in an estate.
Recent changes have made grandparent-owned 529 plans more flexible and removed an important financial-aid concern. That doesn’t mean they’re right for every family.
But if helping your grandchildren with their education is one of the things you want your money to accomplish, they’re certainly worth considering.
If you’d like to talk about how helping your children or grandchildren fits into your retirement, gifting, and estate plan, schedule a complimentary 15-minute call.
A Weekly Perspective on Planning and Markets
Each week, we share The Week in Review — a short collection of articles on
financial planning and wealth management, along with a brief overview for context.
One email per week. No promotions, no sales – just clarity.
This material was written in collaboration with artificial intelligence (ChatGPT) and derived from sources believed to be correct.
Stordahl Capital Management, Inc is a Registered Investment Adviser. This commentary is solely for informational purposes and reflects the personal opinions, viewpoints, and analyses of Stordahl Capital Management, Inc. and should not be regarded as a description of advisory services or performance returns of any SCM Clients. The views reflected in the commentary are subject to change at any time without notice. Nothing in this piece constitutes investment advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Advisory services are only offered to clients or prospective clients where Stordahl Capital Management and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Stordahl Capital Management unless a client service agreement is in place. Stordahl Capital Management, Inc provides links for your convenience to websites produced by other providers or industry-related material. Accessing websites through links directs you away from our website. Stordahl Capital Management is not responsible for errors or omissions in the material on third-party websites and does not necessarily approve of or endorse the information provided. Users who gain access to third-party websites may be subject to the copyright and other restrictions on use imposed by those providers and assume responsibility and risk from the use of those websites. Please note that trading instructions through email, fax, or voicemail will not be taken. Your identity and timely retrieval of instructions cannot be guaranteed. Stordahl Capital Management, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Copyright (c) 2024 Clearnomics, Inc. All rights reserved. The information contained herein has been obtained from sources believed to be reliable, but is not necessarily complete and its accuracy cannot be guaranteed. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness, or correctness of the information and opinions contained herein. The views and the other information provided are subject to change without notice. All reports posted on or via www.clearnomics.com or any affiliated websites, applications, or services are issued without regard to the specific investment objectives, financial situation, or particular needs of any specific recipient and are not to be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. Past performance is not necessarily a guide to future results. Company fundamentals and earnings may be mentioned occasionally, but should not be construed as a recommendation to buy, sell, or hold the company's stock. Predictions, forecasts, and estimates for any and all markets should not be construed as recommendations to buy, sell, or hold any security--including mutual funds, futures contracts, and exchange traded funds, or any similar instruments. The text, images, and other materials contained or displayed in this report are proprietary to Clearnomics, Inc. and constitute valuable intellectual property. All unauthorized reproduction or other use of material from Clearnomics, Inc. shall be deemed willful infringement(s) of this copyright and other proprietary and intellectual property rights, including but not limited to, rights of privacy. Clearnomics, Inc. expressly reserves all rights in connection with its intellectual property, including without limitation the right to block the transfer of its products and services and/or to track usage thereof, through electronic tracking technology, and all other lawful means, now known or hereafter devised. Clearnomics, Inc. reserves the right, without further notice, to pursue to the fullest extent allowed by the law any and all criminal and civil remedies for the violation of its rights.