Borrowing Against Your Investments: When Does It Make Sense?
There are times when you need access to a substantial amount of cash but would prefer not to sell investments to raise it.
Perhaps you're purchasing a new home before selling your current one, helping a family member, or facing a significant expense that wasn't part of your original financial plan.
Selling investments may be the simplest solution. But if those investments have appreciated considerably, selling them could trigger capital gains taxes and disrupt a carefully constructed portfolio.
Another possibility is a securities-backed line of credit (SBLOC), which allows you to borrow against eligible investments without selling them.
For people approaching or enjoying retirement, this can provide valuable flexibility. However, borrowing against your investments also introduces risks that need to be weighed against the potential benefits.
What Is a Securities-Backed Line of Credit?
A securities-backed line of credit allows you to borrow money using eligible investments in a taxable brokerage account as collateral.
Instead of selling stocks, bonds, or mutual funds to raise cash, you pledge certain securities to a lender. The lender establishes a credit limit based on the value and composition of your portfolio.
You generally retain ownership of the investments, which continue to participate in market gains and losses. Interest is charged on the outstanding loan balance, typically at a variable rate.
Unlike a traditional installment loan, an SBLOC may provide flexibility in when you borrow money and repay principal, subject to the lender's terms.
One important distinction is that a typical SBLOC is a non-purpose loan. This means the proceeds generally cannot be used to purchase or trade securities.
Although you retain ownership of the pledged investments, the lender has certain rights over them. Those rights become particularly important if the market declines or the lender changes its collateral requirements.
Why Borrow Against Investments Instead of Selling Them?
Consider a couple approaching retirement with a $2 million taxable investment portfolio.
They want to purchase a new home but haven't yet sold their current residence. They need $300,000 to complete the transaction.
One option is to sell $300,000 of investments.
However, if those investments have appreciated significantly, selling could generate a substantial capital gains tax bill. It could also require liquidating holdings they intended to keep for the long term.
Alternatively, they might borrow $300,000 against their investment portfolio and repay the loan when their existing home sells.
The advantage is straightforward: they can access cash without immediately selling investments or realizing capital gains.
In this example, the loan serves a specific, temporary purpose, and the anticipated home sale provides a potential source of repayment.
That's an important distinction.
Borrowing to bridge a temporary cash need is very different from borrowing indefinitely to support ongoing spending.
Can Borrowing Against Investments Help Reduce Taxes?
One of the primary attractions of securities-backed lending is the ability to access money without triggering an immediate taxable sale.
When you sell appreciated investments, you may owe capital gains taxes on the difference between the sale proceeds and your tax basis.
Borrowing against those investments generally doesn't create a taxable event because you haven't sold anything.
This can be useful when coordinating a large expense with your broader tax and retirement income strategy.
However, avoiding a capital gains tax today doesn't necessarily mean avoiding it permanently.
The loan must eventually be repaid. If you sell appreciated investments to repay it, capital gains taxes may still apply.
There is also the cost of borrowing.
For example, a $300,000 loan at a hypothetical 7% annual interest rate would cost approximately $21,000 per year, assuming the balance and rate remain unchanged.
If the loan remains outstanding for three years, the interest expense would total approximately $63,000.
Depending on the investments' cost basis, your tax situation, and the length of the loan, selling investments and paying the capital gains tax might ultimately be less expensive.
Interest on an SBLOC is also not automatically tax-deductible. Its tax treatment generally depends on how the borrowed funds are used.
The goal should be to evaluate the total financial consequences of borrowing versus selling, rather than focusing exclusively on the immediate tax bill.
What Happens If the Stock Market Declines?
This is the risk that deserves the most attention.
Suppose you have a $2 million investment portfolio and borrow $300,000 against it.
Initially, the loan represents 15% of the portfolio's value.
Now assume the portfolio declines by 30%.
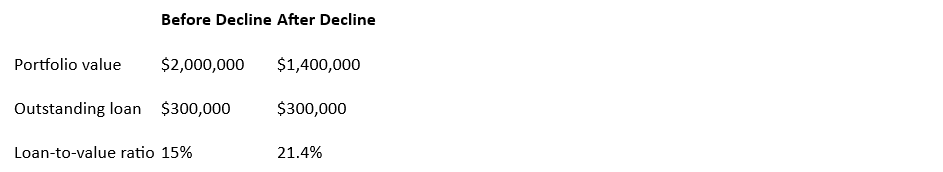
Your investments have declined by $600,000, but you still owe the lender $300,000, plus interest.
A decline of this magnitude wouldn't necessarily trigger a collateral call. That depends on the lender's requirements and the investments pledged.
However, your borrowing cushion has narrowed.
If the portfolio declines further, or the lender changes its collateral requirements, you may be required to provide additional collateral or repay part of the loan.
If you cannot meet those requirements, the lender may sell pledged securities, potentially without advance notice.
For someone approaching or living in retirement, that possibility deserves careful consideration.
A market downturn is already challenging. Being forced to sell investments during that downturn can make it more difficult to recover from losses.
A sound financial plan should provide flexibility during difficult markets, not create additional financial pressure.
How Much Does a Securities-Backed Line of Credit Cost?
Most securities-backed lines of credit have variable interest rates. The rate may depend on the lender, the size of the credit line, and prevailing market interest rates.
Consider the annual cost of borrowing $300,000 at several hypothetical rates.
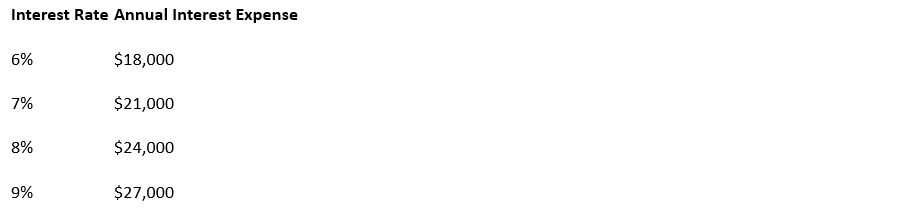
These examples assume the loan balance and interest rate remain unchanged for one year.
A two-percentage-point increase in the interest rate raises the annual cost of a $300,000 loan by $6,000.
That may be manageable for a short-term borrowing arrangement. But over several years, the cumulative expense can become significant.
The cost of borrowing should be compared with the potential capital gains taxes from selling investments, the expected length of the loan, and the borrower's available cash flow.
It's also important to review the lender's terms, including how interest rates are calculated, what investments qualify as collateral, and under what circumstances the lender can demand repayment.
When Does a Securities-Backed Line of Credit Make Sense in Retirement?
We believe securities-backed lending is generally most useful when it addresses a specific financial need and there is a realistic plan for repayment.
Examples might include purchasing a home before selling another property, managing a temporary cash-flow need, or covering a significant one-time expense without immediately liquidating appreciated investments.
In each case, the borrowing arrangement should fit within the broader financial plan.
The situation becomes more complicated when someone uses borrowed money to support ongoing retirement living expenses.
If regular spending requires continual borrowing, the debt may grow while the investments securing it fluctuate in value.
That creates additional risk at a stage of life when preserving financial flexibility is especially important.
Retirees who rely on portfolio withdrawals should be particularly cautious about adding debt secured by those same investments.
Borrowing conservatively, maintaining adequate cash reserves, and having a dependable repayment source can help reduce the risks, although they cannot eliminate them.
Is It Better to Borrow Against Investments or Sell Them?
There isn't a universal answer.
Sometimes borrowing will make sense. Other times, selling investments and paying the resulting taxes may be the better decision.
Before establishing a securities-backed line of credit, several questions deserve attention:
What would selling investments actually cost in taxes? The answer depends on the investments' cost basis, your tax situation, and the timing of the sale.
How long will the loan remain outstanding? A six-month loan is very different from one that remains outstanding for five years.
What happens if interest rates rise? Variable borrowing costs can change the economics of the decision.
Can your portfolio withstand a significant market decline? The amount a lender is willing to advance isn't necessarily the amount you should borrow.
Where will the repayment money come from? Ideally, repayment shouldn't depend on favorable stock market returns.
Are there better alternatives? Existing cash reserves, planned investment sales, or traditional financing may provide a more appropriate solution.
These questions help put the decision in perspective.
The objective isn't simply to avoid selling investments. It's to determine which approach best supports your financial security.
SCM's Perspective
At Stordahl Capital Management, we view securities-backed lending as a financial planning tool, not an investment strategy.
Used thoughtfully, a securities-backed line of credit can provide access to cash while allowing investments to remain in place. It may also create opportunities to coordinate major expenses with tax planning and retirement income decisions.
But borrowing doesn't create additional wealth. It creates a liability secured by assets that can fluctuate in value.
The interest expense is real, market risk remains, and the lender has rights that must be understood.
For people approaching or enjoying retirement, we believe maintaining financial flexibility is particularly important. A borrowing arrangement should support that objective rather than introduce risks that could undermine it.
Sometimes borrowing against investments will be the most practical choice. Sometimes selling investments, using available cash, or arranging traditional financing will make more sense.
The right question isn't simply, "Can I borrow against my investments?" It's "Will borrowing improve my overall financial position after considering taxes, interest costs, repayment, and risk?"
That's the decision worth getting right.
Frequently Asked Questions About Securities-Backed Lines of Credit
Can I borrow against my stocks without selling them?
Yes. A securities-backed line of credit allows you to borrow against eligible investments held in a brokerage account without selling them. The investments serve as collateral, and the amount you can borrow depends on their value, composition, and the lender's requirements.
Is borrowing against an investment portfolio taxable?
Borrowing against investments generally doesn't trigger capital gains taxes because no securities have been sold. However, selling appreciated investments later to repay the loan may create taxable gains. The deductibility of loan interest depends on how the borrowed money is used and applicable tax rules.
What happens to a securities-backed loan if the stock market crashes?
If pledged investments decline substantially in value, the lender may require additional collateral or partial repayment. If you cannot meet those requirements, the lender may sell securities, potentially without advance notice. The specific consequences depend on the loan agreement and collateral requirements.
Are securities-backed lines of credit a good idea for retirees?
They can be useful for temporary liquidity needs when there is a dependable source of repayment. However, using borrowed funds to cover ongoing retirement expenses can increase financial risk, especially during market downturns. The decision should be considered alongside retirement income needs, investment risk, and available cash reserves.
What is the difference between a securities-backed line of credit and a margin loan?
Both arrangements use investments as collateral. However, a typical securities-backed line of credit is a non-purpose loan, meaning the proceeds generally cannot be used to purchase or trade securities. Margin loans may be used to finance securities purchases, subject to applicable rules and lender requirements.
Is it better to sell investments or borrow against them?
The better choice depends on the capital gains taxes associated with selling, the interest cost and duration of borrowing, market risk, and your repayment options. Borrowing may help avoid an immediate taxable sale, but it isn't necessarily the least expensive or lowest-risk approach.
If you're considering borrowing against your investments and want to understand how it might affect your retirement and financial plan, we'd be happy to help you evaluate your options—schedule a complimentary 15-minute call.
A Weekly Perspective on Planning and Markets
Each week, we share The Week in Review — a short collection of articles on
financial planning and wealth management, along with a brief overview for context.
One email per week. No promotions, no sales – just clarity.
This material was written in collaboration with artificial intelligence (ChatGPT) and derived from sources believed to be correct.
Stordahl Capital Management, Inc is a Registered Investment Adviser. This commentary is solely for informational purposes and reflects the personal opinions, viewpoints, and analyses of Stordahl Capital Management, Inc. and should not be regarded as a description of advisory services or performance returns of any SCM Clients. The views reflected in the commentary are subject to change at any time without notice. Nothing in this piece constitutes investment advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Advisory services are only offered to clients or prospective clients where Stordahl Capital Management and its representatives are properly licensed or exempt from licensure. No advice may be rendered by Stordahl Capital Management unless a client service agreement is in place. Stordahl Capital Management, Inc provides links for your convenience to websites produced by other providers or industry-related material. Accessing websites through links directs you away from our website. Stordahl Capital Management is not responsible for errors or omissions in the material on third-party websites and does not necessarily approve of or endorse the information provided. Users who gain access to third-party websites may be subject to the copyright and other restrictions on use imposed by those providers and assume responsibility and risk from the use of those websites. Please note that trading instructions through email, fax, or voicemail will not be taken. Your identity and timely retrieval of instructions cannot be guaranteed. Stordahl Capital Management, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.